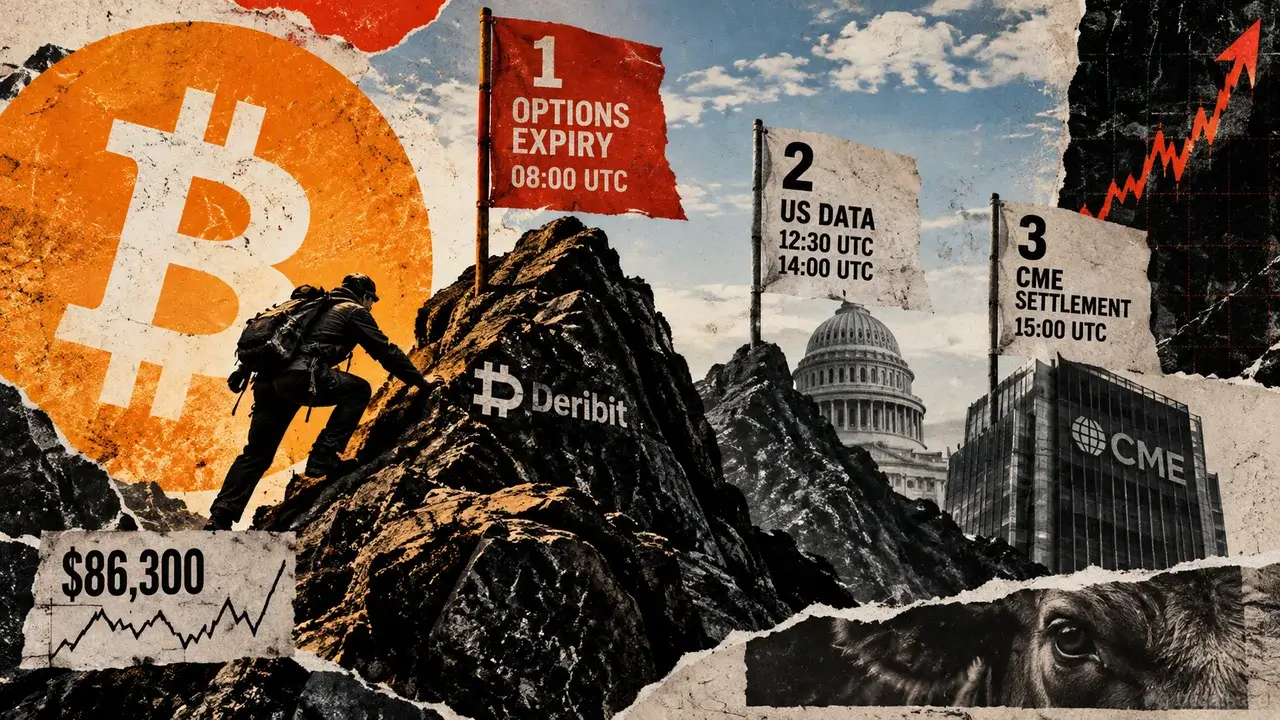
Bitcoin options carrying roughly $16 billion in notional value expire on Deribit at 08:00 UTC on Friday, Sept. 25. Calls account for about $9.6 billion of that open interest and puts for about $6.4 billion.
Bitcoin trades near $86,300 heading into the settlement, after climbing above $85,000 this week. Two US economic releases and the expiry of CME’s September Bitcoin futures follow within seven hours, stacking three separate tests into one trading day.
The equity side settled first
Ledn co-founder Mauricio Di Bartolomeo sees Friday as the second half of an expiry cycle that began on Wall Street.
He said in a note to CryptoSlate that quarterly expirations like September’s are a two-act event. Options on BlackRock’s iShares Bitcoin Trust expired last week in IBIT’s largest single expiration on record, and he described the book as heavily tilted toward calls.
In his account, Bitcoin’s rally through $80,000 pushed many of those calls into the money, and dealers short those contracts bought IBIT shares to stay hedged.
Di Bartolomeo argued that this demand reached Bitcoin itself once it grew large enough to require new IBIT shares, a process that pulls spot Bitcoin into the fund through authorized participants. He expects the Deribit book to inherit the same setup.
He noted:
“If the move continues, the large call blocks at $85,000 and $100,000 are where the same dynamic kicks in on the Deribit book.”
Calls make up about 60% of Friday’s expiring open interest. Estimating how dealers hedge that book requires an assumption about which side of each contract they hold, since exchange data records open interest in aggregate.
ByKaranteli’s open-source gamma model, which its authors present as a map of possible hedging flows under one such assumption, places the largest call wall at $95,000 and the largest put wall at $60,000. It also puts the put-to-call ratio at 0.52 and the zero-gamma level near $71,000.
That zero-gamma level sits where dealer hedging flips character.
Above it, dealers who are net long gamma sell into rallies and buy dips, absorbing moves and pulling price toward heavily populated strikes. Below it, net short gamma forces dealers to buy as price climbs and sell as it falls, amplifying whatever move is underway.
With Bitcoin trading in the $86,000 zone, the model places the market comfortably inside the zone it treats as stabilizing.
| Metric | Current reading | Why it matters |
|---|---|---|
| Total BTC options expiring | ~$16B | Large enough to affect hedging and liquidity conditions |
| Calls expiring | ~$9.6B | Calls dominate the book |
| Puts expiring | ~$6.4B | Downside hedges remain material |
| Call share of OI | ~60% | Shows upside positioning, but not dealer direction |
| BTC spot level | ~$86,300 | Near active strike zones |
| Largest call wall | $95,000 | Main upside concentration in the gamma model |
| Largest put wall | $60,000 | Main downside concentration |
| Zero-gamma level | ~$71,000 | Model’s flip point between stabilizing and amplifying hedging |
Bitcoin options markets are pricing a moderate move
Deribit’s DVOL index stood at 38.1 on Sept. 22, a reading ByKaranteli classifies as very low across five years of history. Friday’s at-the-money implied volatility was also 38.1%, and skew was near neutral, with 25-delta puts and calls both priced near 39.2%.
At that level, a one-standard-deviation move through Friday works out to about $2,720, or 3.15%, placing a rough band between $83,600 and $89,100. That band puts $90,000 at its outer edge and leaves the $95,000 call wall as a distant target.
Deribit sets its delivery price using a 30-minute time-weighted average of its Bitcoin index between 07:30 and 08:00 UTC.
A 2026 study published in Finance Research Letters found intraday Bitcoin price reversals around Deribit expirations that held up under statistical testing, strongest when at-the-money open interest ran high and estimated gamma exposure was negative.
The same research recorded heavier trading in Deribit perpetuals and in the spot venues feeding the settlement index during those windows.
ByKaranteli’s model places the market in positive gamma at current prices, a different condition from the one where the study found the effect strongest. A sharp move that reverses within two hours of 08:00 UTC would fit that documented pattern, and a move that holds through the afternoon’s events would carry broader confirmation.
| Input / Level | Value | Interpretation |
|---|---|---|
| Deribit DVOL | 38.1 | Low by five-year history, according to ByKaranteli |
| Friday ATM implied volatility | 38.1% | Moderate expected movement |
| 25-delta put IV | ~39.2% | Downside protection not heavily bid |
| 25-delta call IV | ~39.2% | Skew near neutral |
| 1-standard-deviation move | ~$2,720 | Approximate expected move through expiry |
| Lower implied band | ~$83,600 | Downside edge of the near-term range |
| Upper implied band | ~$89,100 | Upside edge of the near-term range |
| Nearby upside threshold | $90,000 | Just beyond the implied band |
| Major call wall | $95,000 | Further outside the priced move |
The afternoon handoff
US durable goods orders arrive at 12:30 UTC, four and a half hours past Deribit’s settlement. The University of Michigan’s final September consumer sentiment reading, which includes inflation expectations, lands at 14:00 UTC, and CME’s September Bitcoin futures settle against the CME CF Bitcoin Reference Rate at 15:00 UTC.
The Fed raised its target range to 3.75% to 4.00% on Sept. 16, leaving both data points relevant to rate-sensitive assets.
Once Deribit’s contracts settle, the hedges tied to them unwind or roll into October and December expiries. A macro surprise at 12:30 or 14:00 UTC then meets whatever hedging structure survives that reset.
If the expired book had been stabilizing price, the same surprise could produce a larger move than it did the day before.
US spot Bitcoin ETFs took in $159.5 million on Sept. 17, $433 million on Sept. 18 and $999 million on Sept. 21, according to Farside Investors.
Monday’s rally also included about $647.9 million in short liquidations out of $746.6 million in total liquidations over 24 hours, while aggregate crypto open interest climbed 7.59% to $156 billion.
The rally is supported by spot buying through ETFs and fresh leverage on top of forced short covering.
| Time UTC | Event | Market risk |
|---|---|---|
| 07:30–08:00 | Deribit settlement-price window | Hedging, rolls, and expiry-linked flows may concentrate trading |
| 08:00 | ~$16B BTC options expire | Expiring gamma either disappears or rolls forward |
| 12:30 | US durable goods orders | First macro test after the options reset |
| 14:00 | University of Michigan sentiment | Inflation expectations may affect rate-sensitive assets |
| 15:00 | CME September Bitcoin futures settlement | Second derivatives settlement closes the sequence |
Bitcoin’s rally faces three tests
The bull case has Bitcoin climbing toward $90,000 before settlement while ETF inflows continue and funding stays positive at moderate levels. Traders roll expiring calls into October and December contracts, and price holds through the durable goods, sentiment, and CME events.
Under that path, the $85,000 and $100,000 call blocks Di Bartolomeo flagged become active on the Deribit book, and buyers replace the hedging flows that expired.
The bear case has Bitcoin stalling between $88,000 and $90,000 as ETF flows slow and perpetual futures open interest stays elevated. The strength built into expiry fades once the book settles, and a firmer-than-expected durable goods or inflation-expectations reading hits a market carrying fewer hedges.
In that scenario, Bitcoin slides toward the lower edge of the implied band near $83,600, with $80,000 as the next level beneath it.
Deribit’s settlement opens Friday at 08:00 UTC and CME’s closes it at 15:00 UTC. Bitcoin’s rally holds through that window if the buyers behind it remain in the market once every hedge tied to the expiring contracts has cleared.
