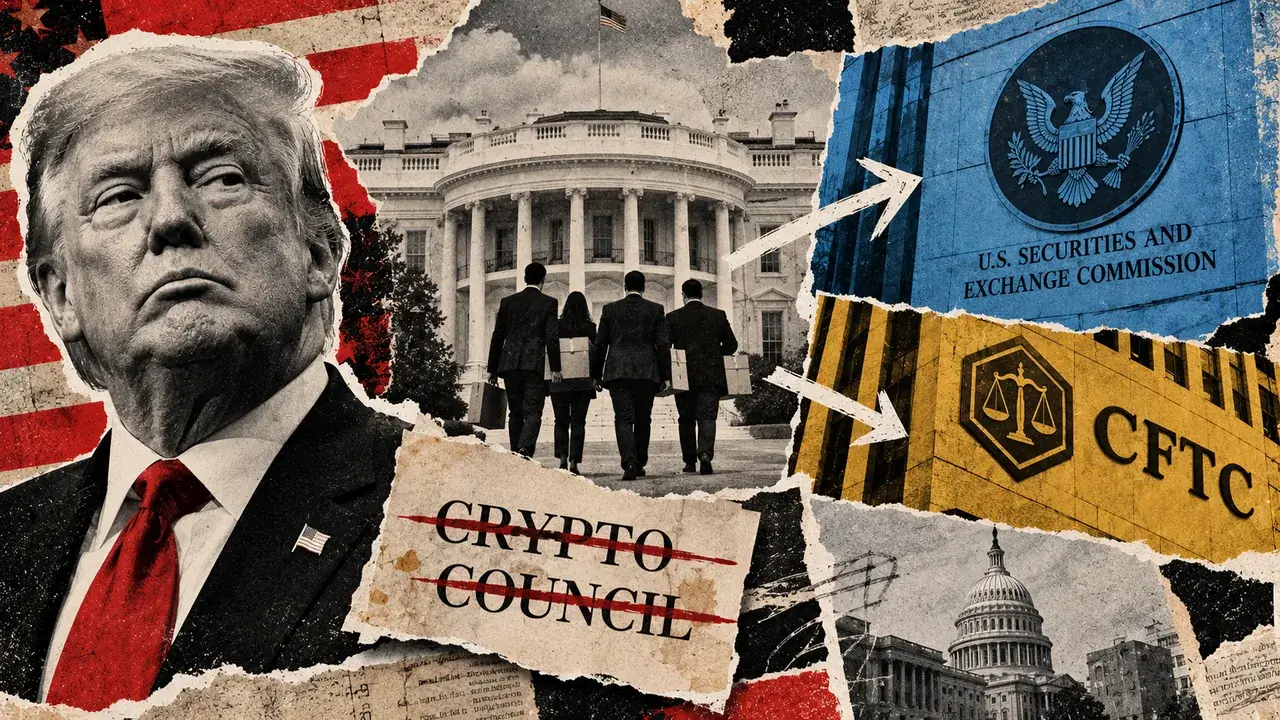
President Donald Trump’s crypto agenda has lost a White House negotiator as Patrick Witt confirms his departure and the administration’s flagship digital-asset legislation remains stalled in Congress.
On Oct. 15, Patrick Witt, executive director of the White House Crypto Council, confirmed his departure after nearly two years in the administration, leaving the government for an undisclosed private-sector role.
In a farewell statement, Witt described his government service as the privilege of a lifetime, thanked Trump and Sacks for their leadership, and highlighted his role in advancing the administration’s cryptocurrency agenda.
He pointed to the passage of the GENIUS Act, which established federal rules for payment stablecoins, and ongoing efforts to advance the CLARITY Act, legislation intended to establish a comprehensive regulatory framework for digital assets.
His exit follows the departures of former council director Bo Hines in August 2025, White House crypto and artificial intelligence czar David Sacks in March, and deputy director Harry Jung in July. No replacement for Witt was identified in his farewell statement.
CLARITY Act loses key negotiator as Senate disagreements persist
Witt’s departure removes a central figure from negotiations over the CLARITY Act.
The House approved its version of the bill in 2025, but efforts to advance it through the Senate have encountered resistance over stablecoin rewards, banking competition and potential conflicts of interest involving Trump’s cryptocurrency businesses.
Those disagreements contributed to the failure of an initial Senate procedural vote in September, leaving the legislation’s prospects uncertain ahead of November’s midterm elections.
Banks have pushed to restrict rewards offered on stablecoin holdings, arguing that such arrangements could divert deposits from traditional financial institutions. Cryptocurrency companies have resisted those restrictions, warning that they could undermine competition.
Democrats have also demanded stronger safeguards addressing Trump’s financial interests in cryptocurrency ventures. Democrats questioned whether those restrictions could be enforced if the Justice Department, rather than states, decided whether to bring an action against the president.
Witt had served as a prominent White House intermediary among lawmakers, regulators and industry representatives. Days before the failed vote, he warned that losing the opportunity to advance legislation could delay comprehensive cryptocurrency rules for years.
Coinbase CEO Brian Armstrong praised Witt’s determination, problem-solving ability, and capacity to work with people holding competing interests.
Alexander Grieve, a government affairs executive at crypto investment firm Paradigm, said Witt had spent two years navigating competing interests, alternating between legislative technician, negotiator and political strategist to keep the CLARITY Act moving.
SEC and CFTC press ahead under existing powers
The Securities and Exchange Commission (SEC) and the Commodity Futures Trading Commission (CFTC) are already pursuing parts of Trump’s crypto agenda through their own policies and actions.
Both agencies have already accelerated efforts to establish regulatory frameworks using their existing statutory authority, reducing their immediate dependence on congressional action.
Under Chairman Paul Atkins, the SEC has pursued rules covering cryptocurrency issuance, custody, and tokenized securities.
The SEC’s initiatives include an Innovation Exemption for trading tokenized NMS stock and an August proposal for regulatory exemptions covering crypto fundraising.
The agency subsequently proposed a cryptocurrency custody framework on Oct. 1, seeking to establish clearer requirements for investment advisers and regulated funds holding digital assets.
The CFTC is pursuing a parallel approach under Chairman Michael Selig.
On Oct. 5, the derivatives regulator opened a consultation on rules governing certain leveraged retail cryptocurrency commodity transactions, including proposals for a specialized registration framework for crypto trading markets.
Selig said the initiative would help establish federal cryptocurrency rules under the agency’s existing powers, outlining plans to move ahead with regulatory action without waiting for Congress.
The developments suggest the two agencies could take on a larger practical role in shaping US crypto policy as White House coordination weakens.
Witt himself acknowledged their importance in his departure statement, specifically thanking Atkins and Selig for their partnership in advancing cryptocurrency legislation over the past year.
However, regulatory action cannot fully replace the certainty offered by legislation.
Atkins previously acknowledged that congressional legislation remained essential to creating durable cryptocurrency rules that future administrations would find harder to reverse.
