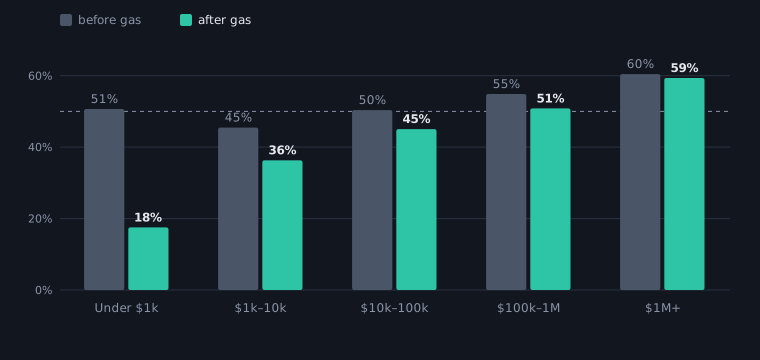
Gas charges tipped many small Uniswap liquidity positions behind simply holding the tokens, according to blockchain data firm Bitquery’s October 16 study. Among closed regular positions below $1,000 in eight sampled Ethereum v3 pools, 51% finished ahead before gas, compared with 18% afterward. The median gas bill for that group was 67 cents.
Uniswap v4’s flash accounting can reduce transfer overhead for liquidity providers, or LPs, who supply tokens for traders to swap. Standard v4 pools retain the price-range mechanics that change what a provider owns as prices move. Fees must compensate for those inventory changes as well as transaction costs.
Bitquery’s return study covers October 14, 2025, through October 13, 2026, in eight Ethereum v3 pools selected for their new-position counts in mid-2026. Its regular-position win rates exclude positions opened and closed within a single block.
Gas matters most to small positions
Across the return study’s eight sampled Ethereum v3 pools, 49% of 71,166 closed regular positions beat holding before gas. After transaction costs, that share fell to 34%.
The effect was particularly sharp below $1,000. A transaction cost measured in cents can consume a narrow advantage over leaving the original tokens in a wallet. Bigger deposits spread that cost over more capital, which helps explain why the before-and-after gap varies so much by position size.
Bitquery’s published size breakdown shows the pattern:
| Deposit size | Beat holding before gas | Beat holding after gas |
|---|---|---|
| Below $1,000 | 51% | 18% |
| $1,000–$10,000 | 45% | 36% |
| $10,000–$100,000 | 50% | 45% |
| $100,000–$1 million | 55% | 51% |
| Above $1 million | 60% | 59% |
Each rounded percentage describes how often a closed regular position beat the holding benchmark. Win frequency differs from the dollar-weighted result: a group can have many small winners and fewer large losers.
For the smallest band, gas separates the two win rates by 33 percentage points. That makes even modest execution savings consequential when a position’s advantage over holding is narrow.
For closed positions, Bitquery compares the tokens returned, plus collected fees, with holding the deposited tokens, using the exit price for both inventories. Gas is then deducted. A position can gain in dollar value while lagging a holding benchmark that gained more.
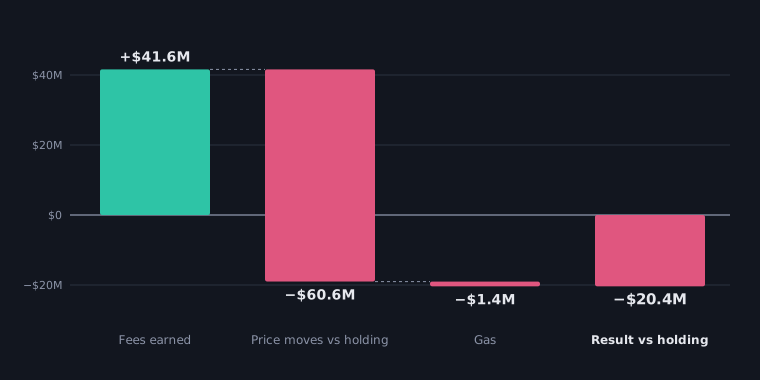
The study’s aggregate collected-fee comparison, which includes positions still open at the cutoff, reports $41.6 million in fees, a $60.6 million inventory shortfall against holding and $1.4 million of gas. Those rounded components reconcile to $20.4 million behind holding. Open positions are valued at the window’s closing price.
Bitquery estimates that the pools generated $59.5 million in total fees, while the position analysis counts $41.6 million collected. The remainder comprises fees still unclaimed at the cutoff or fees that could not be assigned to a position.
Open positions are excluded from the win rates because their unclaimed fees are absent from the study’s event-based accounting. Another 207 positions with fee claims crossed between sibling positions are excluded from per-position figures.
Bitquery counts each transaction’s gas once and splits it across liquidity actions.
What v4 changes for providers
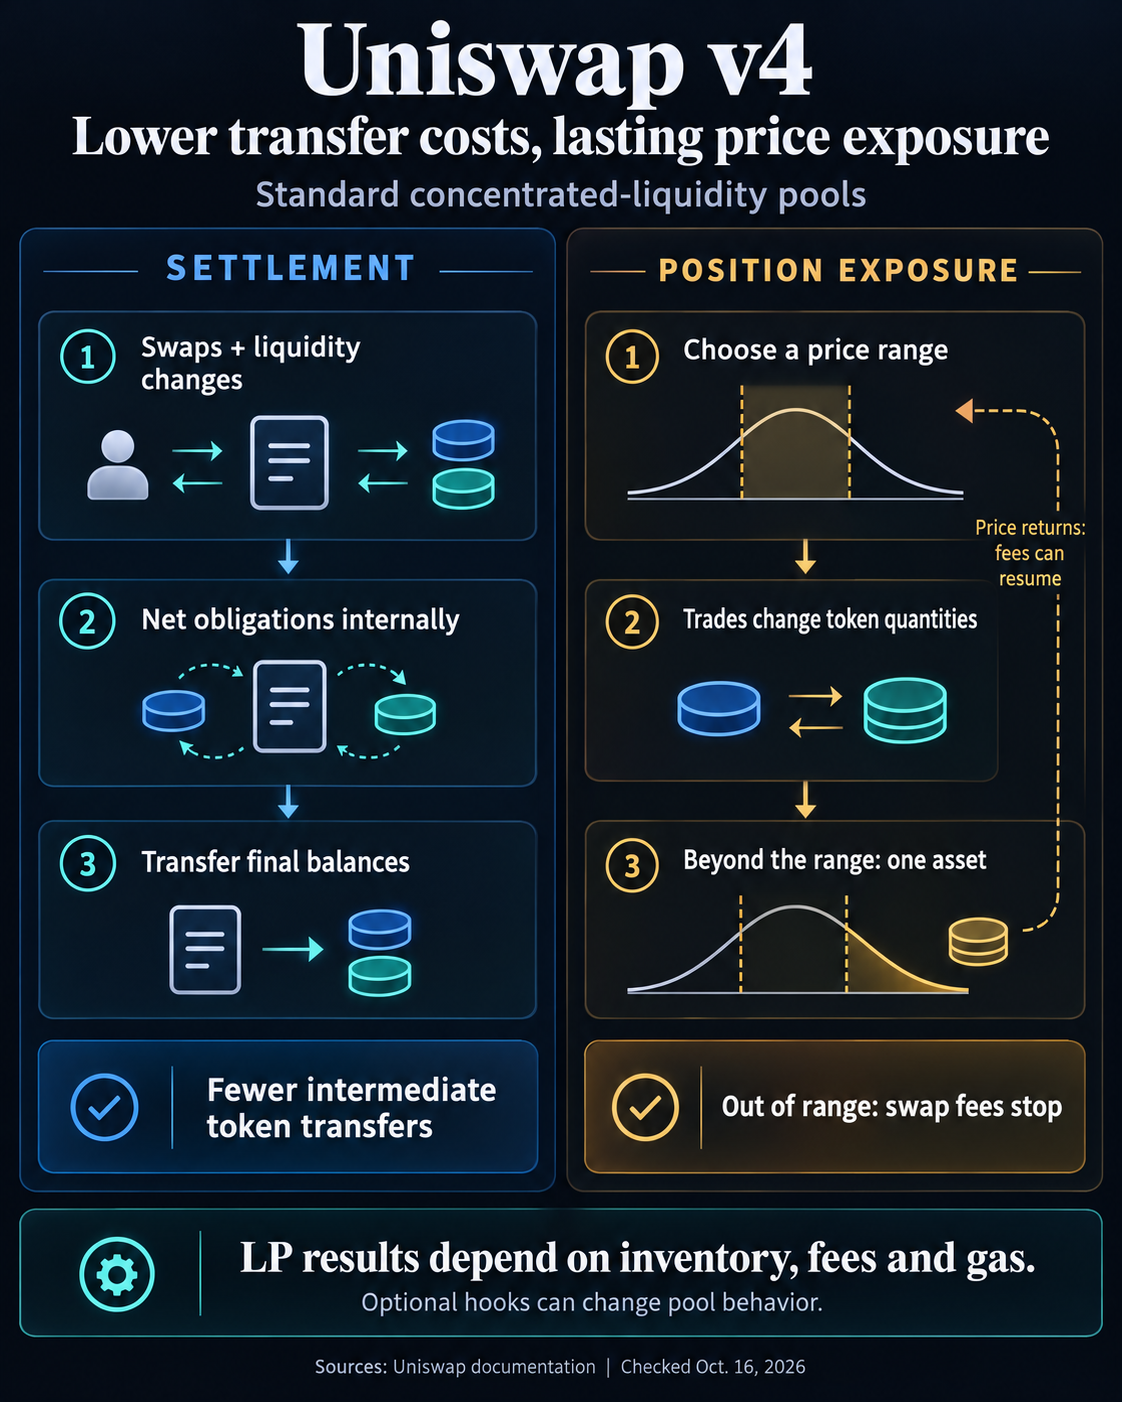
Ethereum transaction fees are paid in ETH. V4’s flash accounting can reduce the work needed to settle swaps and liquidity changes by recording internal amounts owed during an operation and transferring tokens for the final net balance changes.
That is useful when a route crosses several pools or combines a swap with a liquidity deposit. Intermediate tokens need not move repeatedly between separate pool contracts when their obligations can be offset internally.
The saving depends on the transaction route and integration. A provider combining several operations may avoid more intermediate transfers than one making a simpler transaction.
Uniswap’s concentrated-liquidity documentation says v4 retains the same core implementation introduced in v3. Providers choose a price range for their capital. As swaps move the price, the quantities of the two tokens change; beyond a range boundary, a position consists entirely of one asset.
Outside its range, that liquidity stops earning swap fees. It can become active again if the price returns.
A provider can therefore save gas and still finish behind holding if the inventory gap exceeds fee income.
Bitquery’s v3–v4 activity study, corrected October 15, covers July 15 through October 13. It reports v4 liquidity adds rising from about 1,288 per day in the first week to 4,474 in the last, roughly 3.5 times. V3 remained near 1,300 per day.
The corrected comparison excludes zero-size events from both versions. Additions exceeded removals on 88 of 91 days for v4 and 89 for v3. An action count records how often liquidity moves, however, without showing the dollars added or withdrawn.
The standard position-manager route accounted for 77% of v4’s add-count growth. Its users include bots and token launchers alongside other wallets.
The study identifies 3,074 transaction-sending wallets active on both versions, compared with 18 when counted by the contracts calling pools. These are address counts rather than counts of people.
Because v4’s fee records differ from v3’s, Bitquery confines that comparison to liquidity behavior; it does not measure matched v3–v4 position returns.
Dynamic fees face a separate return test
V4 also allows optional hooks that customize pool behavior, including fees, accounting and pricing curves. Those changes can affect economics beyond transfer costs, so standard concentrated-liquidity mechanics cannot determine every hooked pool’s result.
On October 14, Uniswap Labs announced VolatilePair Hook live on Ethereum, starting with ETH/USDC. Its description says separate buying and selling fees are recalculated on each swap using recent price movements.
The hook launched after Bitquery’s October 13 observation cutoff, so it falls outside the study window.
CryptoSlate’s October 1 StablePair analysis examined a related distinction: fee rules can change trading income while providers remain exposed to the tokens they hold. The new v3 figures add a concrete position-size dimension to that problem.
V4 can reduce the transfer bill. Whether a provider beats holding depends on the inventory returned, fees earned and gas paid over the position’s life.