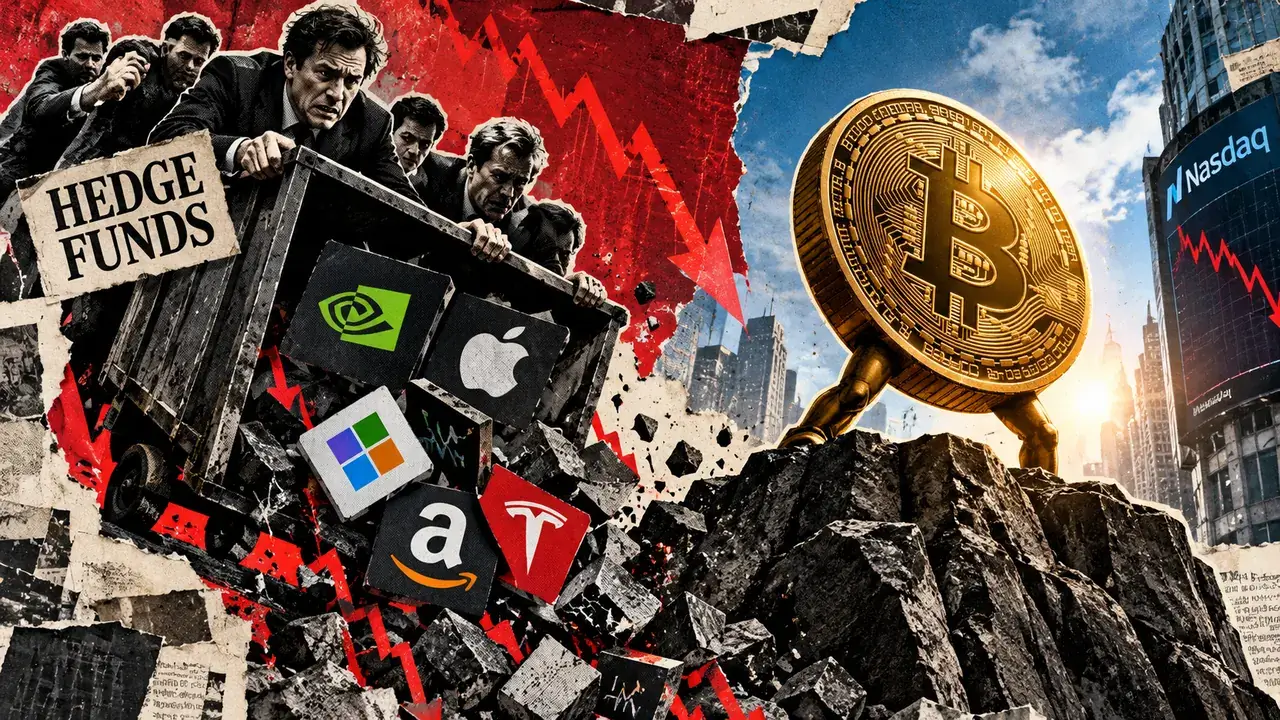
Bitcoin lost less than the Nasdaq-100 in last week’s tech selloff. Hedge funds cut technology positions at the fastest pace since at least 2016 over the five trading sessions through Oct. 15, according to a report citing Goldman Sachs prime brokerage data.
The Nasdaq-100 fell 5.49% from its Oct. 9 close of 30,883.15 to 29,187.55 on Oct. 16. Bitcoin fell about 1.27% over the same dates on UTC daily closes, from $82,546.32 to $81,500.80.
Goldman’s note shows global equities net sold at a pace two standard deviations beyond the prior year’s flow distribution.
Semiconductors took the largest dollar selling, and technology posted its largest reduction in gross positions in two months. Technology accounts for 23.5% of net allocation in Goldman’s global prime brokerage book, in the 90th percentile of the past five years, and hedge fund net leverage fell to a one-year low of 48.6%.
The Bitcoin comparison is preliminary because a UTC close sits four hours from the Nasdaq’s 4 p.m. ET close in October. The difference between these returns is about 4.22 percentage points.
US spot Bitcoin ETFs took in a net $1.72 billion from Sept. 21 through Oct. 16, according to Farside Investors data.
The last two weeks gave back part of that, with net outflows of $678.9 million in the week to Oct. 9 and $228.4 million from Oct. 12 to Oct. 16. Together they equal about 35% of the $2.63 billion that arrived between Sept. 21 and Oct. 2.
Bitcoin’s relative strength came in a week of net redemptions, inside a four-week net inflow. The flow picture improved on Oct. 19: US spot Bitcoin ETFs attracted a net $526.7 million, led by $665.2 million into IBIT.
What derivatives show
CFTC data shows leveraged funds cutting net short exposure in Bitcoin futures by 1,008 contracts, 14.71%, in the week to Oct. 13. Gross shorts fell by 1,219 contracts and gross longs fell by 211, which describes position reduction through closing shorts.
Net shorts remained at 5,844 contracts, equal to 29,220 BTC, and CME open interest fell 3.17%. The Oct. 13 snapshot predates the Oct. 14 to Oct. 16 equity selloff, and short covering as a cause of Bitcoin’s relative strength remains a hypothesis.
How a tech unwind could reach Bitcoin
The IMF’s Oct. 6 research puts hedge funds at about $13 trillion in gross assets and $40 trillion in gross notional exposure.
The most crowded hedge-fund stocks were about 10 percentage points more volatile and suffered peak-to-trough losses about 4 percentage points deeper than the least crowded stocks in the IMF’s historical analysis.
The IMF’s October Global Financial Stability Report names leverage, concentrated exposures, prime-broker stress and correlated redemptions as channels that spread localized disruptions.
In that sequence, deteriorating AI valuations hit crowded positions, margin requirements climb, and funds trim liquid holdings across asset classes, which reaches Bitcoin through shared liquidity needs.
Goldman’s one-year-low net leverage argues for a contained unwind. AI and semiconductor stocks rebounded on Oct. 19.
What the next tests decide
If further selling stays concentrated in AI infrastructure and semiconductor stocks, financing conditions stay orderly and ETF flows improve, Bitcoin could retain its relative strength.
As an illustrative sensitivity, a further 5% Nasdaq-100 decline with an assumed Bitcoin beta of 0.5 and a Bitcoin-specific contribution of 1% to 3% would put Bitcoin between $80,278 and $81,908.
Both inputs are scenario assumptions.
If losses impair collateral values or funding terms, funds cut risk across assets, ETF withdrawals continue, and crypto liquidations grow, Bitcoin trades like a higher-beta risk asset.
A further 10% Nasdaq-100 decline with an assumed beta of 1.2 to 1.6 and a two-point Bitcoin-specific drag implies $66,831 to $70,091. These ranges are conditional stress tests, and the IMF analysis supports the transmission channel while the Bitcoin returns rest on the stated assumptions.
The next CFTC release on Oct. 23 covers positions through Oct. 20, and the Fed’s next policy decision is due Oct. 28.
Rolling beta, ETF flows, CME net exposure, and perpetual funding will show whether Bitcoin’s resilience in an AI-specific selloff extends to broader liquidity stress.
